Agribusiness marketing 2026: where ad budgets really sit
In agribusiness marketing 2026, ad money is moving to digital — and agriculture is no exception. Digital advertising already accounts for roughly 74% of global ad spend and is heading toward ~80%, while newspapers are the one medium in structural decline. For dealers and agri brands that means a print budget now buys a smaller and older audience every year. Below we break agribusiness marketing 2026 down and show what to shift first.
Why the ad market grows on digital alone
The advertising market is growing almost entirely on digital channels, while traditional media survive on the inertia of big brand campaigns. Online video and retail search post double-digit growth, linear TV creeps up by low single digits and loses share, and dailies decline outright. In a leading EU example, Poland, the Q1 2026 market grew 6,7% but newspapers were the only medium with negative momentum (-6,6%). In the agri niche, where you never get the scale of national campaigns, the economics of print advertising deteriorate even faster.
Ad-market momentum, a leading EU market — Q1 2026 (YoY). Online video: +14,4%; Radio: +12,1%; Internet: +8,1%; Linear TV: +2%; Newspapers: -6,6%.
Source: Publicis Groupe Poland, Q1 2026, as a directional EU example.
What this means for agri brands and dealers
For agri brands and dealers it means one thing: every euro in print buys less attention and zero conversion data. Advertisers across every sector are voting with their budgets for digital, because their reach is measurable and cheaper. Commerce and retail media are absorbing budget faster than any other category. The operational takeaway is simple:
- Farm press is suited to brand building, not lead generation.
- The core budget belongs in measurable channels: performance, content, automation.
- Owned video and photo are reusable assets — print is a one-off insertion.
Why the European farmer is online in 2026
The European farmer is online in 2026 — and it is the norm, not the exception. Household internet access across the EU is high, smartphones are the default device, and a majority of farmers have already bought online. A generational handover is sharpening the trend: incoming farm owners consume content like any other B2B segment. Anyone who still reaches farmers through print alone is talking to a shrinking, ageing slice of the market.
Farm digitalisation: internet, smartphone, online buying
Farm digitalisation across the EU is a measured fact, not a forecast. Household internet access exceeds 90% in most member states, the majority of adults shop online, and over half of farmers already have online-purchase experience. Social platforms now work like a search engine — a large share of users research products there before buying. That means the purchase decision on a machine or input starts online, long before any contact with a sales rep.
Generational handover: the young farmer buys online
The generational handover is the single strongest driver of digital consumption in agriculture. Per Eurostat the average EU farmer is 57, only 12% are under 40 and just 6% under 35 — and the European Commission wants to roughly double the young-farmer share to ~24% by 2040. The incoming generation watches machine tests on YouTube and checks purchases in Facebook groups before deciding. With a tractor costing six figures, that buyer researches reviews, field demos and peer opinions intensively — a depth of engagement trade print cannot reproduce.
Why farm-press advertising is losing its effectiveness
Farm-press advertising is losing effectiveness for two independent reasons: circulation is shrinking and conversion data is missing. Trade titles still have loyal readers, but their reach falls year over year while the cost of reaching them rises. At the same time, a print ad cannot show how many readers clicked, asked or bought. For a lead-focused budget, that disqualifies print as a core channel.
The decline of farm-press circulation
Circulation at leading agricultural titles has fallen steadily for years across European markets. A leading EU example, Poland's Top Agrar, dropped from about 52,5k copies in 2018, through 42,9k in 2022, to ~29k distributed in 2024. The same pattern repeats across national farm titles as readers migrate to digital. A smaller print run against a flat or rising rate card means a higher real cost to reach a single reader.
Farm-title circulation decline, EU example (thousand copies). 2018: 52,5k; 2022: 42,9k; 2024: 29k.
Source: PBC and publisher rate cards, 2018–2024 (Top Agrar, Poland).
Cost vs measurability: print hides conversions
Print loses not on the price of a single insertion but on the absence of measurement. A full-page ad in a national trade title runs into the thousands of euros — with no data on clicks, leads or sales. In digital, each of those metrics is visible in analytics and pixels in near real time. The difference is not cosmetic — it is the difference between spending and an investment you can account for:
- Print: no data on clicks, journey or conversion.
- Digital: a full funnel from impression, through click, to lead and sale.
- Print: billed per impression (CPM), not per outcome.
- Digital: billed per outcome (CPL, ROAS) with optimisation on the fly.
Owned channels that deliver measurable returns in agri
Owned channels deliver a better, fully measurable return in agribusiness than print advertising. Email marketing returns roughly $36 per $1, product-page video can lift conversion by up to 80%, and your own photo and video work repeatedly — on the site, in social, in email and in e-commerce. These are assets that stay with the brand, unlike a one-off insertion. Below, two channels worth starting with.
Email marketing and marketing automation in agri
Email and marketing automation are the cheapest measurable relationship channel with farmers and dealers. The average return is about $36 per dollar, and up to $45 in e-commerce — with full control over your list, segmentation and lead scoring. A welcome sequence, seasonal reminders (sowing, spraying, harvest) and service offers can run automatically, without daily team work. We set up the list, automation and sequences fastest on a marketing automation platform retainer.
Video and photo as the farmer's language
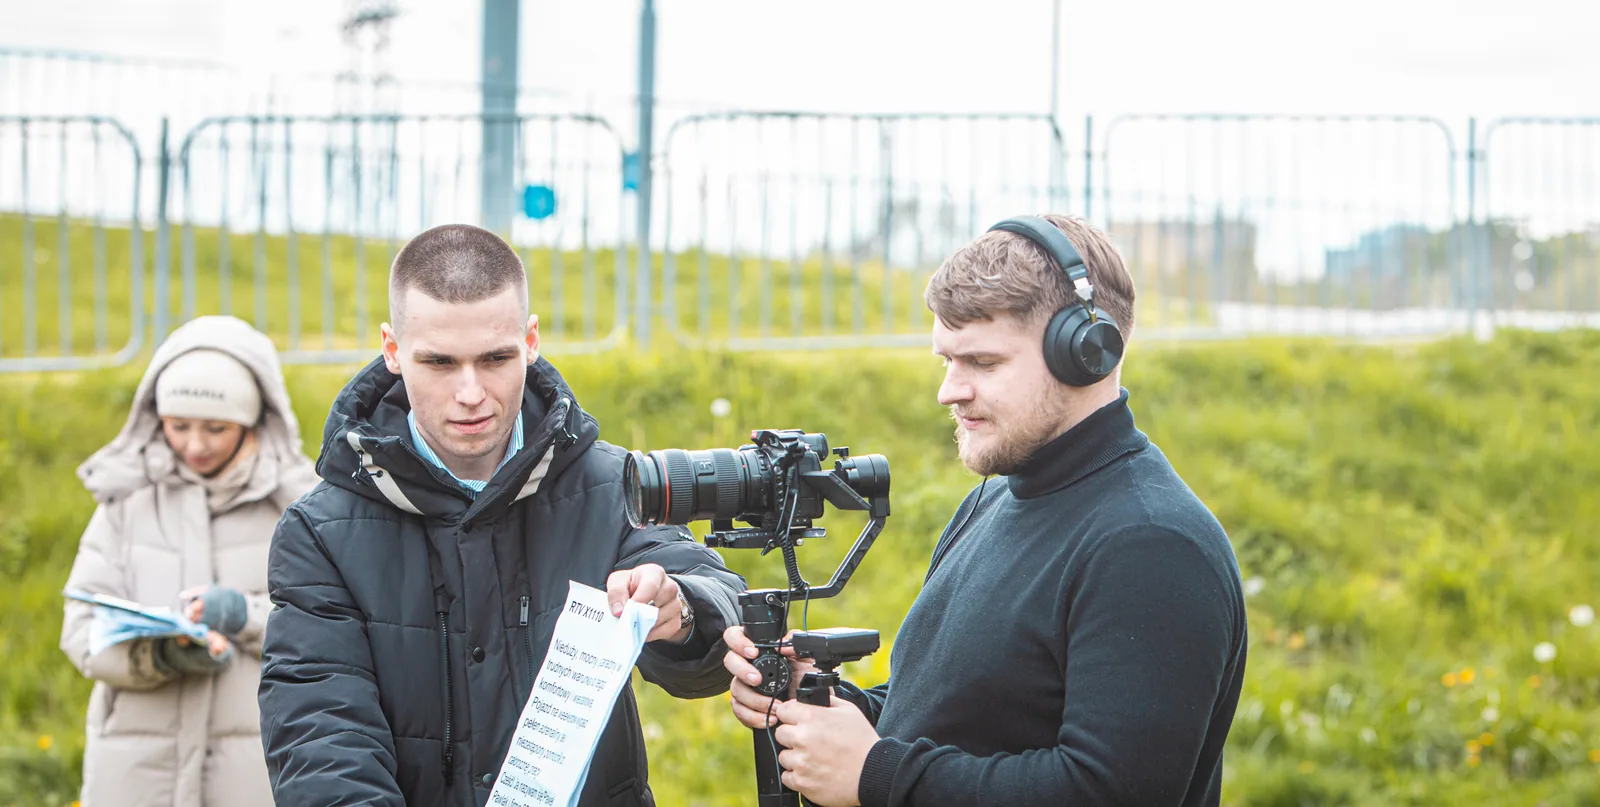
Video is now the farmer's primary language for a purchase decision. YouTube is the world's second-largest search engine, 85% of consumers say a video has convinced them to buy, and users spend 2.6× more time on a page with video. In agriculture the best formats are field tests, machine demos and testimonials — farmers trust a peer's opinion more than an ad. The strongest fuel is authentic video and photo from the field and machine yard, not stock imagery.
- Field tests — the machine or input working in real conditions.
- Demos — operation, specs and service, step by step.
- Testimonials — farmer to farmer, not brand to market.
- Short form (Reels, Shorts) — reach, teasers and behind-the-scenes.
On average, email drives an ROI of $36 for every dollar spent, higher than any other channel.
Performance and retail media in agribusiness marketing
Performance and retail media close out agribusiness marketing 2026 wherever precision and cost per lead matter. Google and Meta campaigns reach the farmer exactly at the moment of buying intent, while retail media use first-party data on real purchases. That is precisely the data print cannot offer. Below we show what cost per lead looks like in digital and why retail media grows fastest.
Cost per lead: digital vs trade fairs and print
Cost per lead in digital is an order of magnitude lower than from trade fairs, and fully measurable — which print is not. An MQL from Meta and Google typically costs €5–20, a qualified SQL €35–180, while a trade-fair lead runs into the high hundreds or thousands of euros. Content and SEO, after the initial investment, can cut cost per lead further. Precise, accountable reach on buying-intent terms and remarketing scales best through programmatic and performance campaigns.
- MQL (Meta/Google): €5–20 — fully measurable.
- SQL (qualified lead): €35–180.
- Content / SEO: ultimately €5–15 per lead.
- Trade-fair lead: €700–1,200 — hard to attribute.
Retail media: the fastest-growing channel
Retail media is the fastest-growing advertising channel in Europe and the natural direction for brands selling parts, accessories and inputs. The category grows roughly 30% a year — three to four times faster than digital advertising overall — and runs on first-party purchase-intent data. That means the ad reaches a buyer who is already searching for the product. For agri it means reaching the farmer at the precise moment of the buying decision.
Retail media will grow by about 30% in 2026, making it one of the fastest-growing advertising channels.
A plan to move from print to digital in agri
The move from print to digital in agri is best phased across three stages rather than done in one jump. The idea is to build measurability first, then shift the centre of gravity of the budget, and finally optimise the channel portfolio. You do not have to drop print overnight — you take away its role as the core and reduce it to a brand-support function. Below is a concrete rollout map.
Stage 1 (0–3 months): the measurability foundation
The first stage builds the infrastructure that lets you measure anything at all. Move 20–30% of the print budget to an owned site and e-commerce with analytics (GA4 + Pixel), a marketing-automation rollout and your first video assets. The benchmark is hard: if the digital cost per qualified lead stays low and email open rates clear 20%, you scale. If you lack the resources to run this in-house, an outsourced marketing team working alongside your experts is the fastest route.
- An owned site and e-commerce with full analytics (GA4 + Pixel).
- A marketing-automation rollout with a list and welcome sequence.
- Your first owned video: one field test plus one machine demo.
Stages 2 and 3: shifting weight and the portfolio
Stages two and three move the core of the budget into performance, content and automation, and reduce print to a supporting role. In stage 2 (3–9 months) you build a video and photo library, launch buying-intent and remarketing campaigns, and enter retail media if you sell parts. In stage 3 (9–18 months) you keep print only where it reaches an older, less digital audience. Build content around the customer's real search terms — supported by SEO for Google and AI search.
- Stage 2: video/photo library + buying-intent campaigns + remarketing.
- Stage 2: enter retail media if you sell parts and accessories.
- Stage 3: print for brand only; core budget in performance + content + automation.